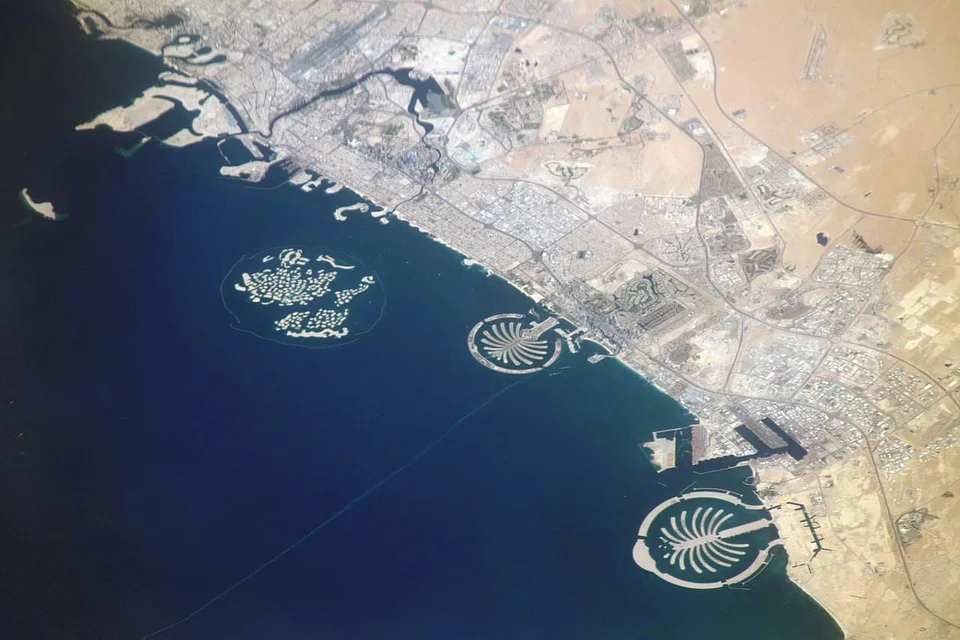
Jebel Ali Village sits in Dubai’s southern corridor, positioned for Al Maktoum International Airport expansion, Dubai South logistics growth, and post-Expo legacy infrastructure. Investors get lower entry tickets than central Dubai with higher gross yield bands, but accept thinner resale liquidity and dependence on government execution timelines.
Unlike mature communities with proven tenant depth, Jebel Ali Village rewards buyers who stress-test employment growth, service charges, and noise contours before they wire deposits.
Insider tip: Visit airport-adjacent stacks at peak flight windows and demand a flight-path map before you treat brochure yields as underwritable.
Jebel Ali Village freehold studios typically start near AED 420,000, one-bedroom apartments cluster around AED 580,000 to 780,000, and two-bedroom units often trade between AED 750,000 and 1.1M, about 15 to 25% below central Dubai peers on a like-for-like finish. Gross yields of 6.5 to 8.5% attract aviation and logistics tenants earning AED 8,000 to 25,000 monthly, yet vacancy of 8 to 12% and service charges of AED 6 to 12 per sqft compress net returns toward 5 to 7% after management. Buyers should pull three Ejari comps in the same phase, map flight-noise contours within roughly 5 km of Al Maktoum runways, confirm Dubai Land Department freehold registration, and keep 12 months of operating reserves before wiring a deposit on southern corridor stock that still depends on Dubai South hiring timelines.
A one-bedroom purchase at AED 680,000 with AED 52,000 annual rent shows about 7.6% gross in Jebel Ali Village, but service charges near AED 6,800 on 850 sqft, management at 6% of rent, maintenance reserves around AED 2,500, and insurance near AED 800 leave roughly AED 38,260 of net income, or about 5.6% net for overseas landlords. Vacancy often runs 8 to 12% versus mature Dubai districts, and 3,000+ southern corridor units completing from 2026 to 2028 can stretch absorption 18 to 24 months in a soft macro year. Stress-test Golden Visa planning only on deeds above AED 2M that are fully paid under ICA rules, and allow 2 to 6 weeks after title for visa processing if residency sits inside the hold thesis.
Why do lower entry prices come with a development trade-off?
Jebel Ali Village apartment prices typically range from AED 420,000 for studios to about AED 1.1M for two-bedroom stock, sitting 15 to 25% below central Dubai peers. Invest Gulf underwriting accepts thinner amenities when foreign buyers need aviation demand within a 15 to 30 minute Dubai South commute.
- Value lever: 15 to 25% discount vs central Dubai
- Demand lever: Dubai South and airport employment
- Trade-off: amenity maturity and resale depth
Economic development drivers
Dubai South ecosystem anchors demand:
- Al Maktoum International Airport (capacity expansion when fully built)
- Dubai World Central free zone and logistics hub
- Dubai South Logistics District
- Aviation industry cluster
- Expo City permanent legacy assets
Employment projections cited in master-plan marketing include tens of thousands of airport, logistics, and Expo-linked jobs. Treat job counts as directional; verify hiring trends quarterly if you rely on rental demand.
Freehold status and foreign ownership
Legal framework: Dubai Land Department (DLD) freehold registration Foreign ownership: 100% freehold for non-UAE nationals in designated zones Golden Visa: Properties at AED 2M+ registered value may qualify (confirm ICA rules on mortgaged stock)
See can foreigners buy in the UAE for nationality and zone checks.
What are typical prices and how do they compare?
Typical prices in the area start at AED 420,000 for studios and typically range AED 580,000 to 780,000 for one-bedroom units, with two-bedroom stock at AED 750,000 to 1.1M. Invest Gulf tells foreign buyers to compare villa bands of AED 1.8M to 3.5M against Dubai South before bidding.
| Property type | Price range | Typical size | Price per sqft |
|---|---|---|---|
| Studio | AED 420,000 to 580,000 | 450 to 600 sqft | AED 900 to 1,100 |
| 1-bedroom | AED 580,000 to 780,000 | 650 to 850 sqft | AED 850 to 1,000 |
| 2-bedroom | AED 750,000 to 1.1M | 900 to 1,300 sqft | AED 800 to 950 |
| 3-bedroom | AED 950,000 to 1.4M | 1,200 to 1,600 sqft | AED 750 to 900 |
| Townhouse | AED 1.5M to 2.5M | 1,800 to 2,800 sqft | AED 800 to 950 |
| Villa | AED 1.8M to 3.5M | 2,200 to 3,800 sqft | AED 750 to 1,000 |
Price comparison with Dubai areas
| Area | Studio | 1-bed | 2-bed | Villa |
|---|---|---|---|---|
| Jebel Ali Village | AED 420K to 580K | AED 580K to 780K | AED 750K to 1.1M | AED 1.8M to 3.5M |
| Dubai South | AED 450K to 620K | AED 620K to 850K | AED 800K to 1.2M | AED 2M to 4M |
| Town Square | AED 550K to 750K | AED 750K to 1M | AED 1M to 1.5M | AED 2.5M to 4.5M |
| JVC | AED 450K to 650K | AED 650K to 900K | AED 850K to 1.3M | N/A |
| Business Bay | AED 700K to 1M | AED 1M to 1.5M | AED 1.4M to 2.2M | N/A |
Off-plan vs ready stock
Off-plan (2026 to 2028 delivery) may price 10 to 15% below ready comparables with 60/40 or 70/30 plans but carries handover delay risk. Ready units support immediate Ejari income and clearer resale comps. Mixed portfolios blend cash flow now with southern corridor growth later; see off-plan vs ready Dubai.
What rental yields and net returns are realistic?
Gross rental yields in the area typically range 6.5 to 8.5% on apartments, with villas closer to 6 to 7.5% before voids. Our analysts model net returns for foreign buyers after AED 6 to 12 per sqft charges against tenant incomes of AED 8,000 to 25,000 monthly.
| Property type | Gross yield range | Annual rent range |
|---|---|---|
| Studio | 7.5 to 8.5% | AED 35,000 to 45,000 |
| 1-bedroom | 7 to 8% | AED 45,000 to 58,000 |
| 2-bedroom | 6.5 to 7.5% | AED 55,000 to 75,000 |
| 3-bedroom | 6 to 7% | AED 65,000 to 85,000 |
| Townhouse | 6 to 7.5% | AED 110,000 to 160,000 |
| Villa | 6 to 7.5% | AED 130,000 to 220,000 |
Net yield example (1-bedroom)
- Purchase: AED 680,000
- Rent: AED 52,000 (7.6% gross)
- Service charge: AED 6,800 (850 sqft at AED 8/sqft)
- Management: AED 3,120 (6% of rent)
- Maintenance reserve: AED 2,500
- Insurance: AED 800
- Net income: about AED 38,260 (5.6% net)
Service charge benchmarks: apartments AED 6 to 12/sqft, townhouses AED 8 to 15/sqft, villas AED 12 to 20/sqft. Compare net bands with Dubai rental yield guide.
Vacancy runs 8 to 12%, higher than mature Dubai, with summer seasonality and temporary oversupply when new phases hand over (often absorbed in 6 to 12 months).
How does infrastructure affect long-term values?
Infrastructure delivery typically drives 15 to 25% of long-term appreciation in southern corridors when rail finishes on schedule, but property values in the area still hinge on Al Maktoum Airport hiring through the 2030s. We treat metro maps as upside for foreign buyers rather than base-case rent growth today.
- Etihad Rail and road widening: corridor upside if delivered
- Metro south: marketing map, not guaranteed rent growth
- Airport phases: jobs and noise both rise into the 2030s
Al Maktoum Airport timeline (indicative)
Cargo operations are live; passenger growth phases stretch toward the 2030s in public planning documents. Implications: more aviation jobs, housing demand, and aircraft noise on some stacks. Visit units at peak flight windows before you buy.
Dubai South and Expo City
Logistics districts, residential phases, and Expo City offices create a combined employment story through 2030. Housing need estimates in marketing exceed Jebel Ali Village unit count, but competing supply in Dubai South caps rent growth in oversupply years.
What risks should investors stress-test?
Key risks in the area typically include infrastructure delay, 3,000+ units completing from 2026 to 2028, aircraft noise within roughly 5 km of runways, and thinner retail than Marina. We keep a 12-month opex reserve for foreign buyers because absorption can stretch 18 to 24 months in soft years.
- Infrastructure delay: metro or road slips vs marketing maps
- Oversupply: 2026 to 2028 handovers pressure rents
- Noise: review contours within 5 km of runways
- Retail gap: thinner dining than Marina for lifestyle tenants
How does Golden Visa planning work here?
Golden Visa planning in the area typically requires a single freehold deed above AED 2M that is fully paid under current ICA rules for foreign buyers. Invest Gulf notes aggregating several units to AED 2M+ gains tenant diversity but adds opex, and visa filing usually takes 2 to 6 weeks after DLD title.
- Single deed path: villa or large townhouse at AED 2M+
- Portfolio path: multiple units totaling AED 2M+ with more opex
- Timeline: title first, then 2 to 6 weeks for ICA filing
How does Jebel Ali Village compare with alternatives?
The area typically offers lower entry tickets and gross yields of 6.5 to 8.5% versus Business Bay or Dubai Marina, with thinner resale liquidity. We see JVC closer on yield but still deeper on day-to-day tenant demand than southern corridor apartment stock in 2026.
| Area | Entry | Yields | Liquidity | Risk |
|---|---|---|---|---|
| Jebel Ali Village | Low to medium | High gross | Lower | Medium to high |
| JVC | Medium | High | Medium | Medium |
| Business Bay | High | Medium | High | Lower |
| Dubai Marina | High | Lower | High | Lower |
Regional UAE context: more infrastructure certainty than distant northern emirate bets, lower ticket than premium Abu Dhabi islands, higher yield potential than established premium Dubai cores.
What investor profile fits Jebel Ali Village?
The area typically fits yield landlords chasing 6.5 to 8.5% gross apartments and owner-occupiers tied to airport or Dubai South employment routes. We treat flip traders as a weak buyer scenario, while Golden Visa foreign buyers need fully paid villa tickets near AED 2M in 2026.
| Profile | Fit | Why |
|---|---|---|
| Yield landlord | Strong | Gross 6.5 to 8.5% on apartments |
| Golden Visa buyer | Medium | AED 2M villas/townhouses available |
| Flip trader | Weak | Liquidity slower than Marina |
| Owner-occupier commuter | Strong | Airport and Dubai South jobs |
How should you build a southern Dubai DD pack?
A due diligence checklist for the area typically requires three Ejari comps in the same phase, two years of service-charge budgets, a flight-path map, and Nakheel NOC status for off-plan stock. We tell foreign buyers to keep six months of reserves because vacancy of 8 to 12% exceeds JVC.
- Ejari comps: three leases in the same phase
- Cost file: two years of service-charge budgets
- Risk file: flight-path map plus Nakheel NOC status
What happens if Dubai South hiring slows?
If Dubai South hiring slows, rent growth in the area typically stalls first on logistics studios, while family townhouses with school access hold better over a 12 to 24 month cash-flow window. We tell foreign buyers who own multiple units to diversify tenant exposure across aviation, warehouse, and Expo office roles.
- Studios: first to stall when logistics hiring slows
- Family townhouses: hold better with school access
- Portfolio rule: diversify tenant sectors, not only buildings
How do service charges compare across property types?
Service charges in the area typically run AED 6 to 12 per sqft on apartments, AED 8 to 15 on townhouses, and AED 12 to 20 on villas with landscaping. We tell foreign buyers comparing JVC net yields to adjust for vacancy of 8 to 12% in soft quarters.
- Apartments: AED 6 to 12 per sqft
- Townhouses: AED 8 to 15 per sqft
- Villas: AED 12 to 20 per sqft with landscaping
What financing options exist for southern Dubai stock?
UAE banks typically approve freehold mortgages on completed Nakheel phases in the area for employed residents, while off-plan purchases follow escrow-linked drawdowns only. Invest Gulf stress-tests foreign buyers on lower LTV bands and AED 2M+ villa tickets for any 6 to 12 month handover slip in practice.
- Ready stock: standard resident LTV on completed phases
- Off-plan: escrow-linked drawdowns only
- Stress test: 6 to 12 month handover slip on AED 2M+ villas
What exit strategy works after a 5-year hold?
A five-year exit in the area typically works best with three years of Ejari history, service-charge receipts, and airport noise disclosure ready for resale buyers. We tell foreign buyers from 2026 entry cohorts to allow 30 to 60 days for conveyancing when nearby phases 4 and 5 hand over later.
- Proof pack: three years of Ejari plus service-charge receipts
- Differentiation: upgrades and lower service-charge stacks
- Timing: 30 to 60 day conveyancing with trustee NOC ready
Which Jebel ali village property investment claims deserve scepticism?
Red flag checks in the area typically pause a purchase when brokers quote yield without service-charge schedules, omit flight-noise disclosure, or lack Trakheesi escrow detail. We tell foreign buyers to request Form F before any SWIFT transfer and walk if freehold status stays unclear for 5 to 10 business days.
- Yield quoted with no service-charge schedule
- Airport-adjacent stack without noise disclosure
- Missing Trakheesi escrow or unclear freehold status
Further reading: Dubai South property guide · Off-plan property Dubai · Dubai rental yield guide · Dubai property investment guide · How to buy property Dubai
Ready to start your Gulf property search?
Get a personalised shortlist matched to your investment goals.
Frequently Asked Questions
Jebel Ali Village offers strong investment potential due to proximity to Al Maktoum International Airport, Dubai South logistics hub, and Expo City. Properties show gross yields of 6.5-8.5% and benefit from infrastructure development, though the area is still developing full urban amenities.
Studios in Jebel Ali Village start from AED 420,000, 1-bedroom apartments range AED 580,000-780,000, and 2-bedroom units cost AED 750,000-1.1M. Villas range AED 1.8M-3.5M. Prices are 15-25% below central Dubai areas.
Yes, Jebel Ali Village is a designated Dubai freehold area where foreign nationals can own 100% of residential property. All purchases are registered through Dubai Land Department with full ownership rights.
Gross rental yields in Jebel Ali Village typically range 6.5-8.5%, with apartments achieving 7-8.5% and villas yielding 6-7.5%. Net yields after service charges and management typically range 5-7%, depending on property type and management efficiency.
Al Maktoum Airport proximity provides employment opportunities and rental demand from aviation/logistics workers, supporting property values. However, some properties may experience aircraft noise. The airport's expansion to become Dubai's main hub is expected to drive long-term appreciation.
Rental demand comes primarily from Dubai South workers, logistics professionals, Expo City employees, and aviation industry staff. The area attracts cost-conscious tenants seeking modern accommodation with good transport links to employment centers.
Key risks include dependence on Dubai South development timeline, potential aircraft noise from airport expansion, limited current retail/dining options, and competition from other emerging Dubai areas. The area is still developing full urban infrastructure and amenities.
Related reading: Dubai property investment guide · Dubai South property investment.
What is the search demand telling you about this district?
Jebel Ali Village draws about 140 property searches a month, and all of it sits on one phrase: jebel ali village villas for sale. That concentration is unusual and useful. It means the audience arriving here has already decided both the community and the product type, which is as close to the transaction as search demand gets. The investment phrasing measured zero, as it did across every Dubai district in the study.
Get a Gulf property shortlist
Tell us your budget and target market. Independent research first; enquiries are matched with licensed local partners. We reply within one business day.