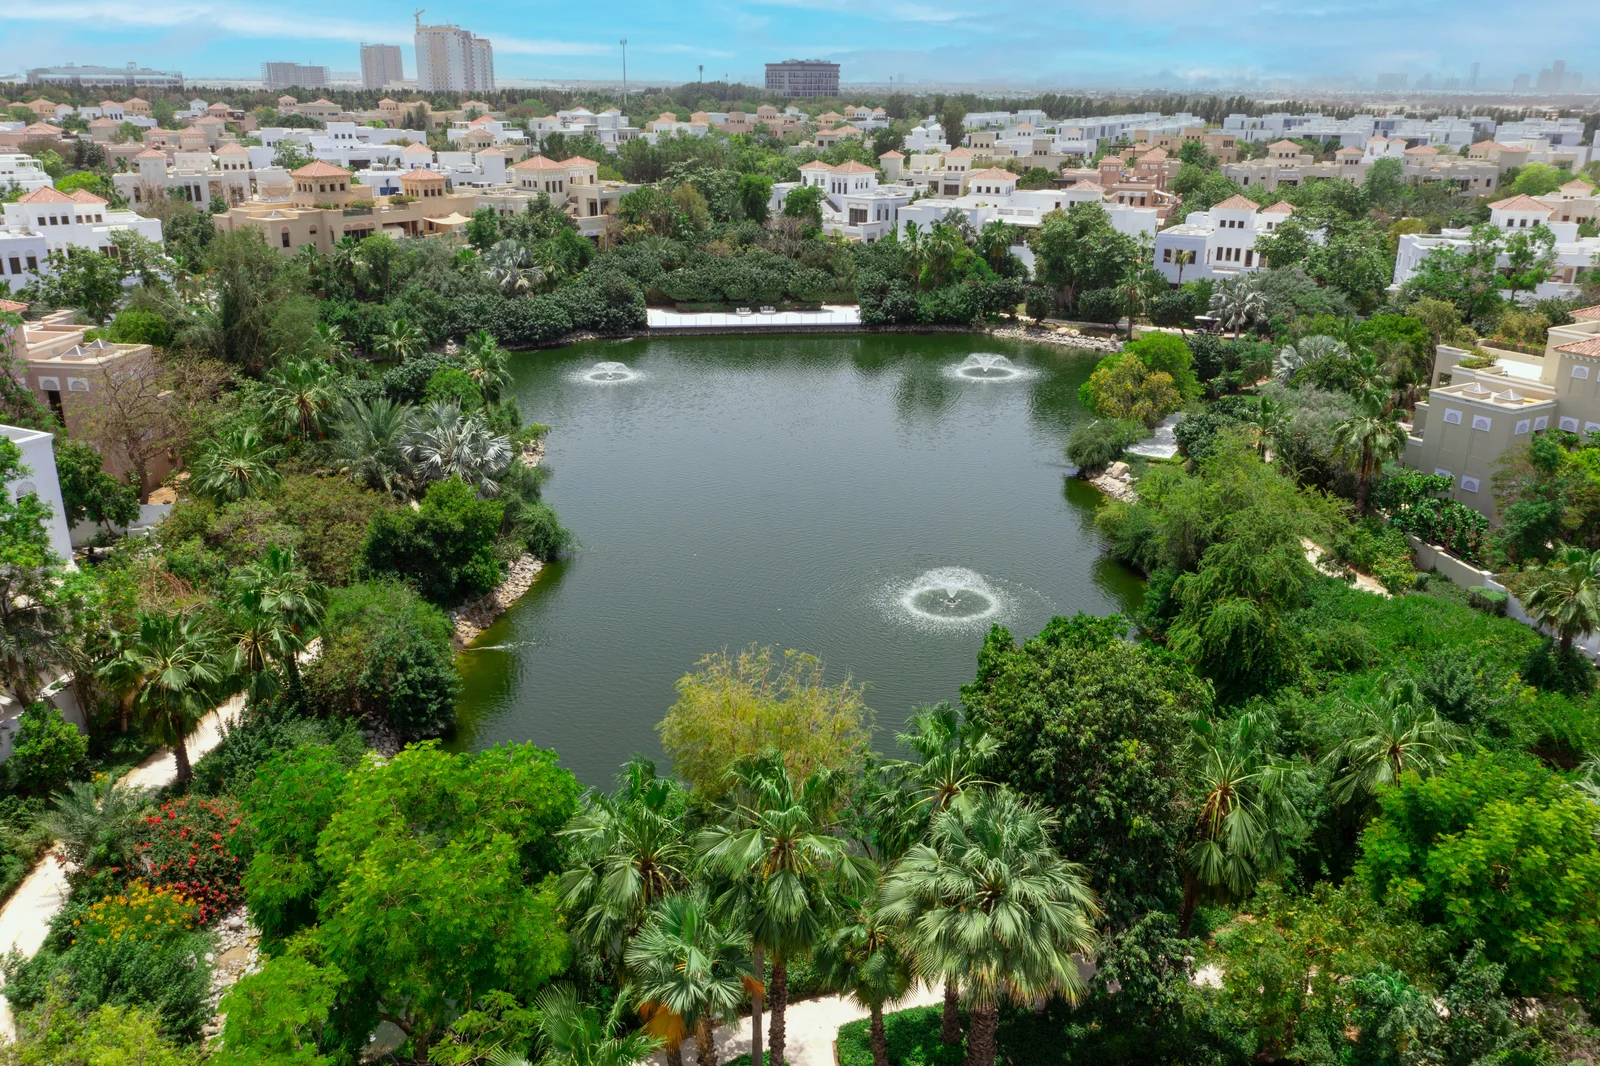
Al Furjan is Nakheel’s west Dubai family and commuter hybrid, townhouses with gardens, mid-rise apartments, and a metro corridor that finally gives Jebel Ali fringe tenants a credible DIFC commute without pretending they live in Downtown.
Compare: Mudon property investment · Best areas buy property Dubai
Is Al Furjan a solid Nakheel buy in 2026?
Al Furjan is a Nakheel freehold community where one-bedroom apartments typically enter at AED 700,000 to 950,000 with 7.5 to 8.5% gross yields, and three-bedroom townhouses near AED 1.8 million to 2.5 million with 6.0 to 7.5% gross before SPA deposit.
| Product | Typical entry (2026) | Gross yield band |
|---|---|---|
| One-bedroom apartment | AED 700K-950K | 7.5-8.5% |
| Two-bedroom apartment | AED 1.0M-1.4M | 7.0-8.0% |
| Three-bedroom townhouse | AED 1.8M-2.5M | 6.0-7.5% |
Invest Gulf underwriting treats Al Furjan as metro-linked mid yield stock, not Dubai Hills lifestyle pricing.
How does metro access change rents and resale?
Metro adjacency at Al Furjan typically shortens Marina and Media City commutes to about 15 to 25 minutes and supports a 5 to 8% rent premium versus pre-metro west Dubai asks, yet walking distance to Ibn Battuta or Route 2020 stations still decides resale liquidity.
| Effect | Investor impact |
|---|---|
| Commute to MOE / Marina | 15-25 min |
| Tenant rent tolerance | +5-8% vs pre-metro |
| Resale narrative | Infrastructure story |
Do not overpay solely on metro branding. Invest Gulf checklists measure station walk time from the exact cluster, not the community name on the brochure.
How do Nakheel phases differ for buyers?
Nakheel phases in Al Furjan typically split western clusters with mature retail and eastern phases still adding amenities, so Ejari-backed rents can diverge by 10 to 15% between buildings even at similar list prices.
| Phase pattern | Retail maturity | Rent verification |
|---|---|---|
| Western clusters | Mature shops | Stronger Ejari depth |
| Eastern phases | Still adding | Amenity timeline risk |
Western phases mix apartments and townhouses with established shops; eastern phases need amenity timeline checks. Pull cluster rents via Dubai rent prices by area before comparing list prices. Our research rejects phase blends that hide unfinished retail.
What does a worked net-yield example look like?
A worked Al Furjan model on an AED 850,000 one-bedroom typically shows about AED 60,000 rent for 7.1% gross, then service charges near AED 14 to 16 per sq ft, 5 to 8% management, and void allowance that lands net near 5.5 to 6.5%.
| Item | AED / rate |
|---|---|
| Purchase | 850,000 |
| Rent | 60,000 |
| Gross yield | 7.1% |
| Indicative net | 5.5-6.5% |
Townhouse gross percentages look lower at 6.0 to 7.5%, but 24 to 36 month family leases can smooth cash flow versus 12 to 18 month apartment churn. Request Mollak service charge history for the exact phase before SPA.
Our underwriting for Al Furjan starts with Mollak filings and station walk time, not metro marketing copy. A one-bedroom bought near AED 850,000 with AED 60,000 annual rent is about 7.1% gross before Nakheel service charges near AED 14 to 16 per sq ft, 5 to 8% management, and a realistic void buffer for 12 to 18 month tenant turns. Net near 5.5 to 6.5% beats many premium family apartments on percentage, yet JVC still competes on headline gross in several clusters. Townhouses near AED 1.8 million to 2.5 million often clear AED 110,000 to 150,000 rent with longer 24 to 36 month holds. Buyers should demand phase-level charge history and confirmed parking before SPA deposit. Parking allocation is the detail that most often surfaces after the deposit rather than before it. Confirm the bay count in writing, because a second vehicle usually means renting a space in a neighbouring building.
Who rents in Al Furjan?
Al Furjan tenants typically include Jebel Ali Free Zone and Dubai South professionals on 12 to 18 month apartment leases, plus families seeking gardens below Arabian Ranches tickets on 24 to 36 month townhouse Ejari.
| Tenant type | Typical lease | Product |
|---|---|---|
| JAFZ / Dubai South pros | 12-18 months | 1-2BR apartments |
| Families with gardens | 24-36 months | Townhouses |
Outstanding-tier schools are usually a bus ride away, which shapes marketing around parking, layout, and commute rather than walk-to-campus prestige. Invest Gulf buyer scenarios favour clusters with allocated parking when underwriting commuter demand.
Which community fits better, Al Furjan or Mudon?
Al Furjan versus Mudon typically wins on Route 2020 metro adjacency and mixed apartment plus townhouse stock, while Mudon wins on quieter villa family feel with lower apartment yield competition for foreign buyers.
| Factor | Al Furjan | Mudon |
|---|---|---|
| Metro | Route 2020 / Ibn Battuta corridor | Car-dependent |
| Product mix | Apartments and townhouses | Townhouses and villas |
| Apartment yield | Higher | Lower |
| Family quiet | Moderate | Stronger |
Compare against Mudon property investment and JVC property investment before chasing headline gross alone. Our research prices Al Furjan metro access as a 5 to 8% rent narrative, not a blank cheque on entry price.
What should you verify on Nakheel off-plan launches?
Nakheel off-plan payment plans at Al Furjan typically run 30/70 or 40/60 construction-linked, so buyers should verify escrow registration, refuse personal-account wires, and model handover delay up to 12 months before underwriting day-one rent.
- Verify escrow on the regulator portal before any transfer
- Model up to 12 months handover delay in the rent start date
- Refuse wires to personal accounts under any payment plan label
Off-plan suits investors who can absorb delay risk; ready stock suits cash-flow buyers who need Ejari within weeks. Our checklists treat missing escrow proof as a hard stop.
What are the main Al Furjan investment risks?
Al Furjan investment risks typically include JVC competition on apartment yield, construction noise in expanding phases, Nakheel service charge resets near AED 14 to 20 per sq ft, and incomplete retail until eastern phases mature.
- JVC yield competition on comparable one-bedroom stock
- Construction noise while eastern phases complete
- Service charge resets near AED 14 to 20 per sq ft
- Incomplete retail until amenity timelines catch up
Red flag checklist: missing Mollak filings, unclear parking for commuter tenants, and gross yield marketed above 10% without verified rent and cost stack. Our underwriting walks away when escrow or developer NOC stays undocumented past the diligence window.
Who should invest in Al Furjan?
Al Furjan typically fits yield-focused buyers on one-bedroom stock near AED 700,000 to 950,000, family investors on townhouses with a 24 to 36 month lease horizon, and Gulf buyers wanting Nakheel branding below Dubai Hills pricing.
| Buyer profile | Fit |
|---|---|
| Yield-first 1BR buyers | Strong |
| Family townhouse holders | Strong |
| Marina liquidity seekers | Weak |
Skip Al Furjan if you need Marina-level liquidity in under 60 days or walk-to-Outstanding schools. Master guide: Dubai rental yield guide.
What financing and service charges should you model?
Al Furjan financing in 2026 typically quotes resident mortgages near 4.5 to 6.5% variable with terms up to 25 years, while non-resident LTV often lands near 65 to 70%, and apartment service charges run about AED 14 to 20 per sq ft annually.
| Charge band | Typical AED per sq ft |
|---|---|
| Apartments | 14-20 |
| Townhouses | 16-22 |
| Villas | 18-25 |
Cash purchases protect net yield from interest; financed buys need stress tests of a +2% rate move against Ejari rent. Our checklists rebuild net after charges, management, and void before SPA.
How should you stress-test Al Furjan numbers before offer?
Stress-testing Al Furjan typically means rebuilding net yield on Mollak service charges by phase, verifying Ejari on the exact building, and comparing ready stock against Mudon and JVC before paying a metro premium.
Off-plan: Verify escrow on the regulator portal and model handover delay up to 12 months.
Ready resale: Stack agency commission, DLD transfer, and trustee fees on top of price; obtain developer NOC if a mortgage is outstanding.
Buy-to-let: Underwrite with real service charge filings, not brochure estimates, and use conservative void assumptions for apartment turnover.
Insider tip: Measure walking minutes from the unit door to Ibn Battuta or Route 2020, not community marketing, and demand two years of Mollak filings before you accept any 8%+ gross claim on Al Furjan apartments.
Al Furjan still fits investors who want Nakheel freehold with metro narrative below Dubai Hills tickets. One-bedroom stock commonly transacts near AED 700,000 to 950,000 with Ejari around AED 52,000 to 68,000 for gross yields near 7.0 to 8.5% before service charges of AED 14 to 20 per sq ft on mid-rise product. Townhouses near AED 1.8 million to 2.5 million often clear AED 110,000 to 150,000 rent on 24 to 36 month family leases with lower churn than apartments. Resale on mid-rise apartments often needs 60 to 90 days when priced from yield, not lifestyle copy. Our research treats a verified station walk and phase-level Mollak history as non-negotiable before SPA. Confirm the parking bay count in writing before the deposit, because a second vehicle usually means renting a space in a neighbouring building at a monthly cost.
Rents, service charges, and Nakheel phase timelines change. Verify Trakheesi, Mollak, and SPA before commitment. Educational content only, not investment advice.
Related reading: Dubai rental yield guide · Service charges Dubai by area · Best areas buy property Dubai · Due diligence Dubai property.
Ready to start your Gulf property search?
Get a personalised shortlist matched to your investment goals.
Frequently Asked Questions
Al Furjan apartments deliver gross yields of 7.0-8.5%; townhouses and villas achieve 6.0-7.5%. One-bedroom apartments at AED 700,000-950,000 generate AED 52,000-68,000 annual rent. Three-bedroom townhouses at AED 1.8M-2.5M achieve AED 110,000-150,000. Net yield after Nakheel service charges (AED 14-20 per sq ft) lands at 5.0-7.0% depending on product type.
Al Furjan suits investors wanting Nakheel master-plan infrastructure at below-Dubai-Hills pricing. Metro adjacency (Ibn Battuta / Route 2020 corridor) improves commute narrative. Family townhouse demand grows as Jebel Ali and Dubai South employment expands. Yield is mid-tier; appreciation linked to metro and Expo corridor legacy.
Yes. Al Furjan is freehold. Foreign buyers receive DLD title deed on apartments, townhouses, and villas. Nakheel is master developer, verify phase-specific handover quality and community charge budgets.
Al Furjan offers stronger metro connectivity and mixed apartment plus townhouse stock. Mudon is pure Dubai Properties villa family community with quieter suburban profile. Al Furjan yields slightly higher on apartments; Mudon townhouses attract longer family tenancy similar to Arabian Ranches at lower price point.
Risks include construction noise in expanding phases, distance from premium schools without bus, competition from JVC on apartment yield, and Nakheel service charge increases. Some phases feel incomplete until retail matures, factor amenity timeline in tenant marketing.
What is the search demand telling you about Al Furjan?
Al Furjan draws about 640 property searches a month, the largest figure among the districts still entering the tree, and it is villa-led: al furjan villas for sale carries 260 of it. The investment phrasing measured zero, as it did in every Dubai district the study covered, and our own Search Console data shows four impressions.
That combination is the argument for this page existing in the form it now takes. There is a real audience, it knows what product it wants, and the site was not reaching it because the page was written for a phrase nobody searches.
Villa-led demand at this price point changes three things, and each differs from the apartment playbook that dominates Dubai property writing.
The community charge is levied on plot area rather than built area, so the annual cost scales with land including garden, driveway and setbacks. Two villas with identical internal space and identical rent can carry materially different charges because they sit on different plots, and the larger plot is the weaker yield unless the rent reflects the land.
The tenant is a family rather than a single professional or a couple, and families move less. That produces longer tenancies and fewer re-lettings across a hold, and each avoided turnover saves both the vacant period and a re-letting commission near 5 percent of annual rent. Across five years that difference is worth more to the realised return than a fraction of a point of headline yield.
The plant is the owner’s responsibility rather than a building’s. Cooling, plumbing, electrics and the roof are the buyer’s problem from the day of transfer, which makes an independent survey covering the systems rather than the finishes worth its cost here. A villa presenting well decoratively can still carry a substantial deferred maintenance liability behind the paint, because finishes are cheap to refresh and plant is not.
The last consequence is about evidence. Villas vary by plot, layout and condition far more than apartments in a single tower do, so a price per square foot averaged across the community blends products that do not compete with one another. Price a specific villa against recent transactions of similar villas on similar plots, and treat anything wider than that as context rather than as evidence.
Where should an Al Furjan buyer start?
Field note on sequence, because the order saves both money and wasted viewings.
Establish the villa type and the plot size before discussing price, since together they set the comparable set and the annual community charge. Pull the Dubai Land Department transactions for that type rather than for the community as a whole. Commission a survey covering the cooling plant, the plumbing, the electrics and the roof rather than the finishes alone, and treat what it finds as a negotiating position rather than a reason to withdraw, because deferred maintenance is normal in stock of this age and it is quantifiable. Confirm that any extension or external modification carries approval, in advance of the no-objection certificate stage rather than during it. Then model the return against the capital committed at transfer, meaning the price plus roughly 6 to 8 percent of entry costs, rather than against the headline price.
Each of those steps is available to any buyer before an offer, none of them depends on an agent’s cooperation beyond producing documents that already exist, and together they answer the questions that actually decide what a villa here is worth.
Get a Gulf property shortlist
Tell us your budget and target market. Independent research first; enquiries are matched with licensed local partners. We reply within one business day.