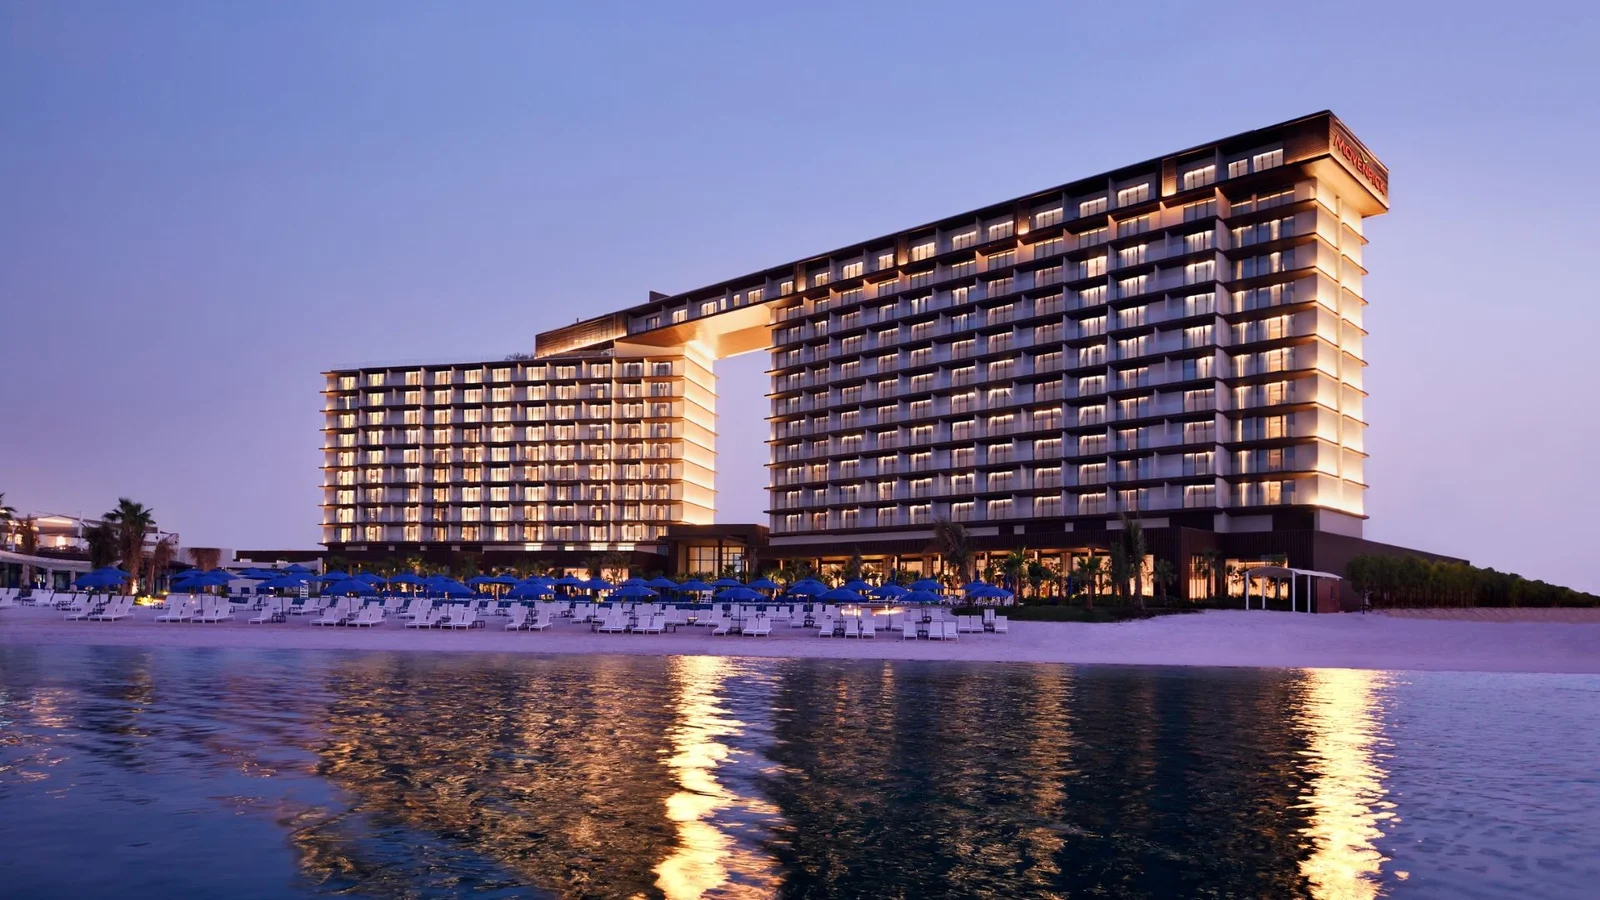
Ras Al Khaimah is a mid-market beach-resort market with one coming event that has reordered the entire investment calculus: the opening of Wynn Al Marjan Island in 2027. The first legal casino operation in the Arab world is a genuine demand catalyst, the kind of structural change that rewrites a real estate market’s long-term trajectory.
The data already shows the impact. Al Marjan Island prices rose 16 to 17% in a single year. The ValuStrat Price Index for RAK reached 123.9, up 12.7% year-on-year. Beachfront branded residences that were priced at AED 1,500 to 1,800 per sqft in 2022 are now trading above AED 2,600 per sqft in off-plan launches.
That movement has two implications. It has made RAK attractive to a broader investor audience. It has also compressed yield on Al Marjan dramatically. This guide separates the two stories, appreciation play versus income play, so you can decide which, if either, applies to your investment thesis.
Ras Al Khaimah underwriting in 2026 starts with two separate theses, not one blended yield story. We model Al Hamra Village listing gross yields near 8% to 9% with ValuStrat net context around 4.5%, while Al Marjan off-plan near AED 2,645 per sqft often compresses long-let gross toward 2.7% to 3.5% until Wynn Al Marjan Island opens in 2027. Beach-resort product still prices about 35% to 45% below comparable Dubai Marina and Palm tickets, yet the secondary market is thinner and a 3 to 7 year hold is the realistic horizon for foreign buyers chasing the USD 3.9 billion catalyst. Entry apartments in Al Hamra can start near AED 500,000 to 700,000; Al Marjan branded stock often starts near AED 600,000 to 1,000,000.
Wynn-linked appreciation is already partly priced in after Al Marjan apartment gains of roughly 16% to 17% year-on-year and a ValuStrat Price Index print of 123.9, up 12.7%. Invest Gulf still separates Singapore Marina Bay Sands case studies showing 40% to 60% district gains within 5 years from RAK’s smaller baseline economy, because foreign buyers who need Dubai-style liquidity inside 24 months will struggle on thin resale. Budget acquisition costs near 5% to 7% of price including about 4% transfer or registration and 2% broker commission, and treat developer “guaranteed rent” above 9% gross at AED 2,600 per sqft as marketing until leased comps appear. A 3 to 7 year hold through the 2027 opening remains the base case; exits forced inside 2 to 3 years should not rely on brochure absorption.
Insider tip: If a listing yield needs AED 195 per sqft rent to hit 7.5% gross at today’s Al Marjan entry price, ask for three signed leases at that rent before you underwrite income.
What does the RAK market look like in 2026?
RAK in 2026 is a beach-resort market already pricing a 2027 Wynn opening, and Invest Gulf tracks ValuStrat at 123.9 (+12.7% YoY) with Al Marjan apartments up about 16% to 17%. Beach product still sits roughly 35% to 45% below Dubai Marina and Palm equivalents.
| Metric | Figure | Signal |
|---|---|---|
| ValuStrat Price Index | 123.9 | +12.7% YoY, among fastest in UAE |
| Al Marjan Island apartment YoY | +16.8 to 17.2% | Pre-Wynn pricing in |
| Al Hamra Village villas YoY | Up to +42% | Undersupply in villa segment |
| Al Marjan share of RAK listings | ~55% | Dominant pipeline concentration |
| Wynn Al Marjan opening | 2027 | Primary demand catalyst |
| RAK Golden Visa threshold | AED 2 million | Same as rest of UAE |
| Personal income tax | 0% | UAE-wide |
| Price vs Dubai Marina/Palm | 35 to 45% cheaper (equivalent beach-resort product) | Entry-point advantage |
Singapore Marina Bay Sands comparisons often cite 40% to 60% gains within 5 years; RAK’s smaller baseline means magnitude is uncertain.
How do Al Marjan, Al Hamra, and Mina Al Arab compare?
Al Marjan, Al Hamra, and Mina Al Arab are three different risk books, and we underwrite Al Marjan near AED 2,645 per sqft as a forward-priced Wynn option with 2.7% to 3.5% long-let gross. Al Hamra leads income with 8% to 9% listing gross and about 4.5% ValuStrat net context.
| Metric | Al Marjan | Al Hamra | Mina Al Arab |
|---|---|---|---|
| Average price | ~AED 2,645 / sqft off-plan | ~AED 1,417 / sqft apartments | ~AED 1,677 / sqft |
| YoY apartments | +16.8 to 17.2% | +11.5% | +7.5 to 11.3% |
| Listing gross yield | 7.5 to 8.5% aspirational | 8 to 9% | 7.5 to 8.5% |
| VPI / net context | ~2.7% | ~4.5% | More predictable family leases |
| Thesis | Appreciation to 2028-2030 | Income + moderate upside | Lower-risk family hold |
Al Hamra Village: The Established Yield and Lifestyle Zone
Al Hamra is RAK’s mature integrated resort with roughly 4,000 residential units, golf, marina, and Waldorf Astoria demand. Apartment entry from AED 500,000 suits yield sizing; villa gains up to +42% reflect undersupply that may persist for several more years.
Mina Al Arab: Master-Planned, Family-Oriented
Mina Al Arab is RAK Properties’ lagoon master plan with family tenants on long-term leases. Full absorption can take a decade, which caps near-term appreciation versus Al Marjan.
Which RAK district fits income versus appreciation goals?
Income-first foreign buyers typically fit Al Hamra Village at 8% to 9% listing gross and about 4.5% ValuStrat net context, while appreciation-first capital fits Al Marjan if a 3 to 7 year hold to the 2027 Wynn opening is realistic. We steer Mina Al Arab toward conservative family leases rather than casino-tourism upside.
- Choose Al Hamra when rent coverage matters before 2028
- Choose Al Marjan when you can fund holding costs with thin initial yield
- Choose Mina Al Arab when public-developer transparency matters more than upside
How could Wynn Al Marjan reshape RAK demand?
Wynn Al Marjan Island is a USD 3.9 billion integrated resort opening in 2027, and we model post-opening STR income for well-located units rising toward AED 120,000 to 140,000 per year versus AED 70,000 to 80,000 pre-Wynn. Corporate staffing demand and brand signal can re-rate the district, but delays would extend the yield-negative period.
Why this matters for real estate:
- Short-term rental demand: gaming tourists are high-yield STR customers once permits and occupancy mature
- Corporate demand: managerial hospitality staffing creates long-term leases that do not exist today
- Brand signal: comparable casino districts in Singapore and Macau revalued surrounding stock after operations stabilised
Downside risks include regulatory change, opening delays, and tourism shocks. None is the base case, but each belongs in the price.
What transaction costs should Gulf buyers budget in RAK?
RAK acquisition costs typically run 5% to 7% of purchase price, and our analysts model about 4% transfer or registration plus 2% broker commission. Abu Dhabi still has an edge at roughly 2% transfer for pure cost comparisons.
| Cost line | Typical range |
|---|---|
| Transfer / registration | ~4% |
| Broker commission | ~2% |
| NOC / admin | Deal-specific |
| Total cash stack | 5% to 7% |
Can RAK property qualify for the UAE Golden Visa?
RAK freehold in designated zones can support the UAE Golden Visa at the AED 2 million threshold, the same floor as Dubai and Abu Dhabi, and we still separate residency sizing from yield. Al Hamra usually offers better income economics; Al Marjan offers more appreciation optionality with thinner initial rent.
- Property must be registered in the buyer’s name in a designated zone
- Confirm current ICA / GDRFA rules before SPA
- Do not assume off-plan instalments automatically qualify before title
How should buyers vet RAK developers and escrow?
Developer and escrow checks are mandatory before off-plan deposits, and we treat missing RAK Land Department registration as a hard stop for foreign buyers even when branding looks international. Delays of 12 to 18 months are common and should be modelled in cash flow.
- Confirm RAK Land Department project registration
- Verify escrow account separate from the developer operating account
- Request audited financials or parent-company backing
- Check construction progress against payment milestones on site when possible
How does RAK stack up against Dubai for Gulf investors?
RAK typically offers beach-resort entry 35% to 45% below Dubai Marina and Palm pricing, while Dubai offers deeper secondary liquidity and stronger STR depth that we prefer for foreign buyers who may need an exit inside 24 months. Al Marjan off-plan near AED 2,645 per sqft should not be compared only on brochure yield.
| Factor | RAK | Dubai beach core |
|---|---|---|
| Entry pricing | 35% to 45% lower for like-for-like resort product | Higher |
| Secondary liquidity | Thin | Deep |
| STR maturity | Growing, uneven | Mature in many towers |
| Hold horizon | 3 to 7 years typical for Wynn thesis | 3 to 7 years with more exit options |
Who does RAK suit, and who should look elsewhere?
RAK suits foreign buyers who can hold 3 to 7 years through the 2027 Wynn opening and accept thinner resale, and we steer away anyone needing Dubai Marina liquidity or strong Al Marjan income before 2028. Conservative capital uncomfortable with development-risk concentration should prefer Al Hamra or Mina Al Arab.
RAK does not suit:
- Investors needing immediate liquidity
- Buyers targeting short-let income before Wynn opens
- Anyone who must exit within 2 to 3 years at above-entry prices
What is the realistic RAK market outlook through 2028?
RAK through 2028 is a split market: Al Hamra villa gains near +42% are not a repeatable annual rate, while Al Marjan remains a Wynn-linked appreciation book that our team underwrites with thin initial yield. Mina Al Arab stays the most conservative public-developer path with family leases.
- Al Hamra apartments offer more reasonable 2026 entry than extended villa prints
- Al Marjan needs hold power into 2028 to 2030 without rent dependency
- Supply from multiple branded launches can cap near-term upside
What red flags should pause an RAK purchase?
Red flags include Al Marjan gross yield pitches above 9% at entry prices above AED 2,600 per sqft, off-plan developers missing RAK Land Department records, and guaranteed-rent promotions that we treat as priced-in marketing. Singapore comparisons without market-size adjustment are another pause signal.
- Al Marjan gross yield projections above 9% without leased comps
- Off-plan developer with no RAK Land Department record
- Guaranteed rental income from the developer as the sole underwriting input
- Marina Bay Sands comparisons that ignore RAK’s smaller baseline
Where should you read next in the RAK guide cluster?
Next reading should deepen Dubai and Abu Dhabi comparables and Golden Visa mechanics, and Invest Gulf routes foreign buyers to freehold eligibility and off-plan payment guides before any AED 500,000+ RAK deposit. Use the cluster to stress-test liquidity versus Wynn appreciation.
- Dubai Property Investment Guide
- Abu Dhabi Property Investment Guide
- Can Foreigners Buy Property in the UAE?
- Golden Visa Mortgage Property UAE
- Off-Plan Payment Plans in Dubai
Considering property in Ras Al Khaimah?
Get an independent shortlist matched to your income, liquidity, and holding-period goals.
Frequently Asked Questions
RAK offers a specific investment case: beach-resort lifestyle property at 35 to 45% below Dubai Marina and Palm Jumeirah prices, with gross yields of 6 to 9% in established communities and a major demand catalyst in the form of Wynn Al Marjan Island (the first legal casino in the Arab world, opening 2027). It suits investors comfortable with a smaller, less liquid market and a 3 to 7 year hold horizon aligned to the Wynn opening.
Wynn Al Marjan Island is a USD 3.9 billion integrated resort opening in 2027 on Al Marjan Island, the first legal casino operation in the Arab world. Comparable casino-resort openings in Singapore (Marina Bay Sands, 2010) and Macau produced 40 to 80% real estate price appreciation in surrounding districts within 5 years. Al Marjan Island prices have already risen 16 to 17% YoY on speculative buying. Whether the full Wynn effect materialises depends on regional visitor volumes.
Al Hamra Village leads on yield in the established market: listing-based gross yields of 8 to 9% with ValuStrat's VPI model showing approximately 4.5% net context yield, reflecting a combination of long-term lease income and moderate capital appreciation. Mina Al Arab follows at 7.5 to 8.5% listing gross. Al Marjan Island is primarily a capital appreciation play at current pricing, gross yield at today's entry prices tracks around 2.7 to 3.5% on long-term lets.
Yes. RAK has established designated freehold zones for foreign nationals, including Al Marjan Island, Al Hamra Village, and Mina Al Arab. All transactions register with the Ras Al Khaimah Land Department. The Golden Visa threshold is AED 2 million, the same as Dubai and Abu Dhabi. Properties must be registered in the buyer's name in a designated zone to qualify.
RAK's Al Marjan Island offers comparable beachfront living to Dubai Marina at approximately 35 to 45% lower per-sqft prices. Al Marjan off-plan projects currently average around AED 2,645 per sqft; Dubai Marina runs AED 1,900 to 2,600 per sqft for established secondary stock. The trade-off: Dubai Marina has a far larger secondary market, an established STR market, and a broader tenant base. RAK suits long-hold investors; Dubai Marina suits those who need liquidity.
RAK's transaction fee structure broadly mirrors the rest of the UAE: a 4% transfer fee (or equivalent registration fee with the RAK Land Department), broker commission of 2%, and NOC fees for resale. Total acquisition costs for cash buyers typically run 5 to 7% of purchase price. Off-plan contracts require registration with RERA-equivalent oversight under the RAK Land Department.
Entry-level apartments in Al Hamra Village start from around AED 500,000 to 700,000. On Al Marjan Island, pricing has risen sharply, off-plan studios and one-bedrooms in branded residences start from AED 600,000 to 1,000,000 for smaller units, with larger apartments above AED 1,500,000. Mina Al Arab offers entry points from approximately AED 600,000 for apartments. Villa pricing across all areas starts from AED 1,500,000 and rises sharply for beachfront product.
The primary risks are: (1) the Wynn catalyst is real but not guaranteed, regulatory changes, delayed opening, or lower-than-expected visitor volumes would reduce appreciation potential; (2) the RAK secondary market is thin, reselling a unit quickly is harder than in Dubai or even Abu Dhabi; (3) Al Marjan yield at current entry prices is marginal, buyers acquiring at 2026 prices for income rather than appreciation face low initial returns; and (4) supply pipeline is significant, with multiple branded residence projects launching simultaneously.
RAK's STR market is growing but not yet comparable to Dubai. Airbnb and Booking.com operate in RAK, and holiday home permits are required. Al Hamra Village has an established short-let track record given its resort infrastructure. Al Marjan Island STR potential is high in theory once Wynn opens, but occupancy in 2024 to 2025 is modest compared to mature Dubai neighbourhoods. Buyers projecting Dubai Marina to style STR returns in RAK are getting ahead of current market reality.
RAK Properties is the flagship government-backed developer, primarily active in Mina Al Arab. Al Hamra Real Estate Development built Al Hamra Village (integrated resort, golf course, mall). RAKEEN is another public entity. On Al Marjan Island, a wave of private and international developers, including branded-residence operators, has launched off-plan projects since 2022. Developer due diligence matters more in RAK than in Dubai given the shorter track records.
Related reading: Dubai Property Investment Guide · Abu Dhabi Property Investment Guide · Can Foreigners Buy Property in the UAE? Full Legal Guide · Golden Visa Mortgage Property UAE · Off-Plan Payment Plans in Dubai.
Get a Gulf property shortlist
Tell us your budget and target market. Independent research first; enquiries are matched with licensed local partners. We reply within one business day.