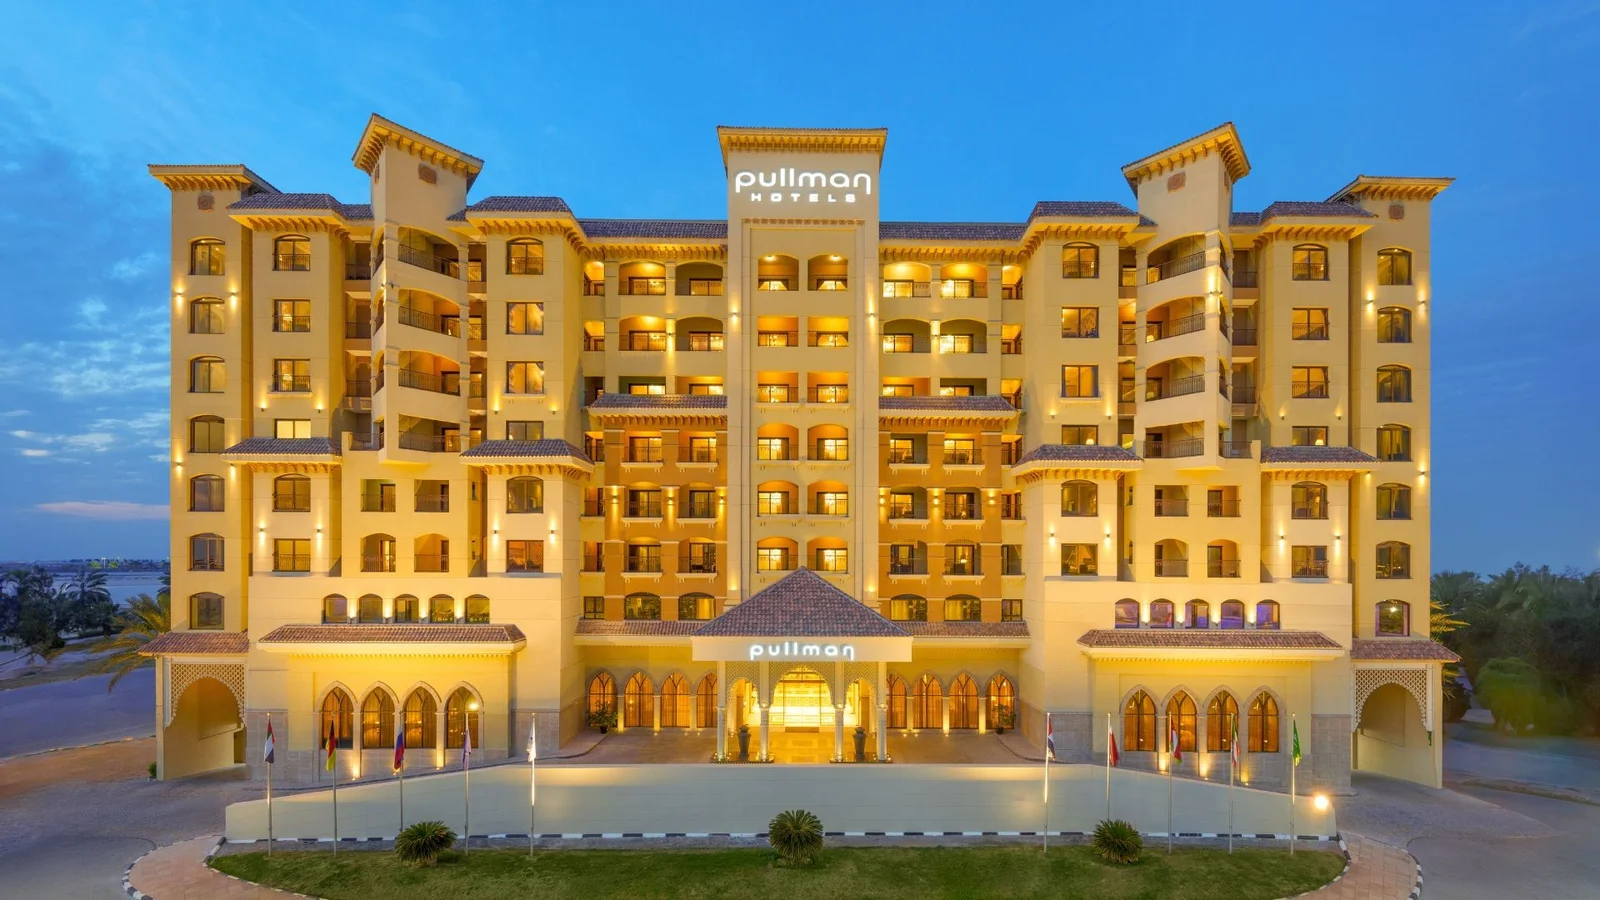
Ras Al Khaimah off-plan in 2026 is two markets in one emirate: Al Marjan Island appreciation play ahead of Wynn Al Marjan (2027), and established-community yield play in Al Hamra Village and Mina Al Arab. Conflating them produces bad investment decisions.
See Ras Al Khaimah Property Investment Guide and Al Marjan Island Property Investment.
How does RAK off-plan compare to Dubai in 2026?
RAK off-plan typically offers beach-resort product at 35% to 45% lower psf than Dubai Marina benchmarks, with a Wynn catalyst Dubai lacks, while liquidity and tenant depth stay thinner. Our underwriting treats RAK as a long-hold capital play and Dubai as the liquidity sleeve.
- Registration: RAK Land Department versus DLD/Oqood
- Transfer fees: about 4% in both, confirm live rates
- Commute to Dubai employment: often 45 to 60 minutes at peaks
- Catalyst: Wynn Al Marjan targeted for 2027
Is Al Marjan Island an appreciation or yield play?
At 2026 launch pricing Al Marjan typically models 3% to 5% gross long-term yield, with appreciation tied to Wynn Al Marjan opening in 2027. Invest Gulf rejects Al Marjan as an immediate income sleeve when the rental floor is thin.
- Launch psf on branded stock often AED 2,400-3,200
- Speculative price rises of 16% to 17% YoY already priced some optimism
- Risk: Wynn delay, regulatory change, or weaker visitor volumes
- Hold period: plan 5 to 7 years through opening and maturation
Al Marjan off-plan developer landscape
Branded residence operators and international developers dominate new supply. Due diligence checklist:
- RAK Land Department registration and escrow
- Developer completed project in UAE or equivalent market
- Construction progress on an active building zone
- Service charge estimate: branded residences run high
- STR permit framework post-Wynn (not yet mature)
Why does Al Hamra suit yield-focused off-plan buyers?
Al Hamra suits yield buyers because established community infrastructure typically supports 7% to 9% gross on apartments at AED 900-1,600 psf, below Al Marjan premiums. Invest Gulf prefers Hamra when income must arrive inside 24 months of handover.
- Lower psf than Al Marjan branded launches
- Gross yield 7% to 9% on apartments
- Established STR track record in prior phases
- Villa segment showed strong appreciation in 2024-2026 cycles
See Al Hamra Village Property Investment.
Where does Mina Al Arab sit between yield and growth?
Mina Al Arab typically models 6% to 8% gross on government-backed RAK Properties stock with moderate appreciation optionality. We use Mina as the middle sleeve between Hamra income and Marjan speculation on a 5 year hold across a 12 month underwriting window on a 5 year hold assumption.
- Developer credibility: RAK Properties government-backed profile
- Tickets often AED 600K-1.2M for apartments
- Target yield: about 6% to 7% on recent phases
- Lagoon product without full Al Marjan premium
What are 2026 RAK off-plan price and yield bands?
Price and yield bands in 2026 typically split by community, with Al Marjan branded at AED 2,400-3,200 psf and 3% to 5% gross, versus Al Hamra extensions at 7% to 9%. Invest Gulf refuses blended emirate averages in underwriting.
| Community | Launch psf (AED) | Ticket (AED) | Gross yield band | | | | | | | Al Marjan branded | 2,400-3,200 | 800K-5M+ | 3-5% | | Al Marjan standard | 1,800-2,400 | 800K-2M | 4-6% | | Al Hamra extension | 1,200-1,800 | 700K-2M | 7-9% | | Mina Al Arab | 1,000-1,400 | 600K-1.2M | 6-8% |
How do RAK off-plan payment plans differ from Dubai?
Milestone plans are common, and buyers should budget RAK Land Department transfer near 4% separately from Dubai DLD if they hold in both emirates. Invest Gulf spreads construction cash over 24 to 36 months in base cases across a 12 month underwriting window on a 5 year hold assumption.
| Stage | Typical RAK plan | Cash-flow note | | | | | | Booking | 5-10% | Non-refundable risk | | Construction | 30-50% | Spread 24-36 months | | Handover | 40-60% | Often needs mortgage or cash | | Post-handover | Optional 2-3 years | Verify interest if any |
How does an Al Marjan appreciation sleeve work?
An Al Marjan appreciation sleeve typically accepts 3% to 5% gross today when the primary thesis is Wynn-driven capital growth over 5 to 7 years. Invest Gulf marks that sleeve unacceptable when the buyer needs rental income in year one.
- Low yield acceptable only if appreciation thesis delivers
- Unacceptable if household cash flow needs rent now
- Stress Wynn visitor volumes as a range, not a promise
- Keep escrow and SPA registration non-negotiable
How does a Mina Al Arab AED 750,000 studio yield play work?
A Mina Al Arab studio near AED 750,000 typically targets a yield play with moderate RAK appreciation optionality around 6% to 8% gross. Our analysts model service charges and vacancy across 12 months before calling the ticket safe income.
- Ticket: about AED 750,000 illustrative studio
- Gross yield band: 6% to 8%
- Government-backed developer narrative helps financing optics
- Still verify escrow and handover realism
How does RAK versus Dubai off-plan stack for Gulf investors?
RAK typically suits long-hold capital plays while Dubai suits liquidity and diversified tenant pools, with RAK beach-resort psf often 35% to 45% below Marina. Invest Gulf allocates both only when hold period and cash-flow tolerance are written down.
| Factor | RAK off-plan | Dubai off-plan | | | | | | Registration | RAK Land Department | DLD / Oqood | | Transfer fees | ~4% (confirm rate) | ~4% DLD + trustee | | Liquidity | Thinner | Deeper | | Beach-resort psf | 35-45% below Marina | Marina benchmark | | Catalyst | Wynn Al Marjan 2027 | Diversified employment |
What supply pipeline risk sits on Al Marjan?
Multiple branded residences launching together can compress rents and resale at handover clusters typically so foreign buyers should assume overlapping completions across 2027 to 2028. Invest Gulf haircuts brochure rents when three peer projects hand over in the same 12 months across a 12 month underwriting window on a 5 year hold assumption.
- Simultaneous branded launches are the core oversupply risk
- STR rules may still be immature at first handovers
- Exit liquidity is thinner than Dubai Marina
- Stagger exits away from the densest handover quarter
Does RAK off-plan count toward UAE Golden Visa?
RAK off-plan can count toward UAE Golden Visa when registered value meets the AED 2 million threshold, matching Dubai. We verify SPA value and title path with RAK Land Department before any visa timeline is sold across a 12 month underwriting window on a 5 year hold assumption.
- Threshold: AED 2 million, confirm current official rules
- Freehold designation must appear on SPA
- Registration path is RAK Land Department, not DLD
- Joint ownership splits need careful reading
Which Off-Plan in Ras Al Khaimah signals justify walking away?
Red flags that should pause a purchase include buying Al Marjan for immediate rental income and signing an SPA with no RAK Land Department registration typically both of which our research treats as severity-one issues within the first 90 days. with written exits.
- Buying Al Marjan for immediate rental income (use Hamra or Mina instead)
- No RAK Land Department registration on SPA
- Service charge estimates missing from branded stock
- Handover clusters ignored in the exit plan
- Yield quotes that blend Marjan and Hamra averages
Which buyer profiles fit RAK off-plan?
Buyer profiles typically split into capital appreciation investors for Al Marjan and income investors for Al Hamra and Mina extensions, with hold periods of 5 to 10 years. Invest Gulf refuses mixed mandates that want Marjan yield at Hamra prices. with written exits.
- Appreciation sleeve: branded Marjan, 7 to 10 year patience
- Yield sleeve: Hamra or Mina, income inside 24 months of handover
- Moderate sleeve: non-branded Marjan or premium Mina, 5 to 7 years
- Weak fit: sub-3-year flip assumptions on thin liquidity
Which related RAK and UAE off-plan guides should you read next?
Related reading typically starts with Ras Al Khaimah property investment guide and Al Marjan Island property, then Dubai off-plan comps. We keep Golden Visa rules in a separate tab for any AED 2 million path across a 12 month underwriting window on a 5 year hold assumption.
What timeline should you assume for Wynn Al Marjan?
Opening is targeted for 2027, so base investment cases should use conservative visitor volume with upside as optionality across a 5 to 7 year hold. We never use the bull case as the planning assumption across a 12 month underwriting window on a 5 year hold assumption.
- Base case: conservative tourism delivery
- Bull case: upside only, not the underwriting floor
- Delay risk: extend hold and stress cash flow for 12 to 24 months
- Monitor official Marjan and Wynn updates quarterly
How does RAK off-plan registration work?
Registration requires RAK Land Department filing, escrow verification, and a transfer fee near 4% at title, which is not Dubai DLD/Oqood. We track separate systems when clients hold both emirates across 5 years across a 12 month underwriting window on a 5 year hold assumption.
- SPA signed with developer
- Register with RAK Land Department (not DLD)
- Escrow verification per RAK regulations
- Transfer fee at title (approximately 4%: confirm current rate)
- Handover and snagging per developer process
Are branded residence premiums worth paying?
Branded residences typically suit capital appreciation and STR operator investors, not yield-first buyers, because service charges and launch psf near AED 2,400-3,200 compress income. Invest Gulf sends income mandates to non-branded Marjan or Al Hamra instead.
JW Marriott Residences Al Marjan:
- Launch pricing: AED 2,400-3,200/sqft
- Payment plan: 40/60 with post-handover component
- Handover: Q2 2027
- Thesis: Bonvoy-linked STR optionality
Nikki Beach Resort & Residences:
- Launch pricing: AED 2,200-2,800/sqft
- Payment plan: 30/70 construction linked
- Handover: Q1 2028
- Thesis: beach-club lifestyle demand
Al Hamra Village expansion projects
Al Hamra Waterfront Residences and Golf Residences Phase 3 typically launch near AED 1,200-1,800/sqft for apartments, with rental expectations around 7% to 8% gross on existing-phase evidence. Invest Gulf favours these when income is the mandate.
Mina Al Arab developments
RAK Properties Bay Residences typically launch near AED 1,000-1,400/sqft with target yields around 6% to 7% gross based on Mina track record. Our research treats government-backed delivery optics as helpful, not a substitute for escrow checks.
What due diligence framework fits RAK off-plan?
Due diligence should cover permits typically contractor track record, competition in the same handover window, and realistic service charge projections across at least 12 months of ops assumptions. We run the checklist below before any SPA across a 12 month underwriting window on a 5 year hold assumption.
- Building permits and municipality approvals current
- Soil and foundation reports reviewed
- Utility connection agreements in place
- Competition from peer projects in the same price band
- Management company track record on service charges
How do banks finance RAK off-plan?
Bank LTV is often lower than Dubai, with valuers applying 5% to 10% haircuts, so foreign buyers should submit to multiple lenders over a 4 to 8 week process. We prefer pre-approval before SPA when cash buffers are thin across a 12 month underwriting window on a 5 year hold assumption.
- HSBC UAE examples: about 60% LTV, heavy diligence
- Standard Chartered: about 65% LTV on some branded stock
- Longer processing than Dubai equivalents is common
- Prepare for valuations below purchase price
Which strategy matrix row fits your mandate?
Strategy rows typically match yield, moderate appreciation, or aggressive Al Marjan branded bets to hold period and cash-flow tolerance. We write the row before naming a project across a 5 to 10 year hold across a 12 month underwriting window on a 5 year hold assumption.
Yield strategy (income first):
- Al Hamra Golf Residences Phase 3
- RAK Properties Bay Residences final phases
- Select Al Hamra waterfront extensions
- Expected gross yield: 7% to 9%
Moderate appreciation strategy:
- Budget AED 1.2M-2.2M per unit
- Expected gross yield: 4% to 6% with Wynn upside
- Hold: 5 to 7 years
- Financing: 50% to 65% LTV
Aggressive appreciation strategy:
- Budget AED 2M-5M+ per unit
- Expected gross yield: 2% to 4%
- Hold: 7 to 10 years minimum
- Financing: 30% to 50% LTV or cash
When is the best time to enter RAK off-plan?
2026 still prices pre-Wynn opening for many launches typically so entry can make sense when payment plans spread cash over 2 to 3 years. We watch handover clusters that could overlap with a planned exit window in 2029 to 2030. with written exits.
Immediate advantages (2026 purchases):
- Pre-casino opening pricing still available on some stock
- Payment plans spread outflow over 2 to 3 years
- First-mover branded inventory still exists
Near-term risks (2026-2027):
- Multiple projects competing for the same buyer pool
- Wynn delays could affect sentiment for 12 months or more
- Rising construction costs can stress weaker developers
How should RAK versus Dubai off-plan be concluded?
Strategic conclusion typically gives RAK higher upside with higher risk, and Dubai more predictable near-term rent and resale depth across a 5 to 10 year portfolio. We set allocation by liquidity need, not by brochure adjectives across a 12 month underwriting window on a 5 year hold assumption.
Data reflects RAK Land Department and market pricing through Q1 2026. Wynn opening timeline is indicative. This guide is for information purposes only and does not constitute investment advice.
Insider tip: Underwrite Al Marjan as a 5 to 7 year capital sleeve with a forced 3% to 5% yield floor; if that floor breaks your cash-flow rules, buy Hamra or Mina instead of hoping Wynn fixes year-one income.
What off-plan checks matter most in Ras Al Khaimah?
Off-plan checks that matter most are letting rules, service charge history, Dubai commute reality, resort-adjacency seasonality, and exit liquidity windows longer than Dubai Marina norms. We use the tables below as a red-flag screen across a 5 to 10 year hold.
| Diligence item | RAK coastal note | | | | | Letting rules | Tourism permits are building-specific | | Service charges | Verify phase history | | Commute to Dubai | Rare office days only for most buyers | | Resort adjacency | Weekend traffic and seasonality | | Exit liquidity | Longer marketing windows than Dubai Marina |
| Hold idea | Practical rule | | | | | Under 3 years | Usually too short for RAK off-plan | | 5+ years | More realistic for amenity maturity | | Income first | Prefer handed-over stock when possible |
RAK off-plan is two sleeves: Al Marjan appreciation ahead of a targeted 2027 Wynn opening at roughly AED 2,400-3,200 psf and 3% to 5% gross, versus Al Hamra and Mina income at 6% to 9% gross on lower psf. Invest Gulf compared payment plans that spread construction cash over 24 to 36 months with bank LTVs often 5% to 10% below Dubai norms after valuation haircuts. Beach-resort product can price 35% to 45% below Dubai Marina, but secondary liquidity is thinner and Dubai employment tenants still face 45 to 60 minute peaks on school weeks. Golden Visa paths still hinge on about AED 2 million registered value with RAK Land Department confirmation. Do not blend Marjan and Hamra yields into one emirate average when underwriting. Underwrite RAK on the assumption that Wynn opens late rather than on time; a 12-month slip is survivable on a 5-year hold and fatal on a 2-year flip.
RAK off-plan underwriting should separate Al Marjan branded launches at AED 2,400-3,200 psf from Al Hamra extensions that still model 7% to 9% gross, because conflating them produces false comfort on year-one income for cash-flow buyers. Invest Gulf stress-tests Wynn visitor volumes across a 5 to 7 year hold, assumes overlapping handovers in 2027 to 2028 can compress rents, and requires RAK Land Department registration plus escrow before any SPA deposit beyond a trivial booking fee. Payment plans commonly leave 40% to 60% due at handover, so mortgage pre-approval with a 5% to 10% valuation haircut belongs in week one of diligence. Exit windows in 2029 to 2030 are more realistic than sub-3-year flips on thin resale depth. Check that the escrow account named in the SPA matches the RAK authority record before the first payment.
Further reading: RAK Al Marjan Island Infrastructure Upgraded for Wynn 2027 works through RAK Al Marjan Island Infrastructure Upgraded for Wynn.
Looking for the best off-plan projects in the Gulf?
Get a curated shortlist of verified launches with payment plan details.
Frequently Asked Questions
RAK off-plan suits two distinct strategies: capital appreciation on Al Marjan Island ahead of Wynn Al Marjan opening (2027), and yield on established communities like Al Hamra Village. Al Marjan off-plan at 2026 launch prices models low gross yield (3-5%) but strong appreciation potential. Al Hamra ready and near-completion stock models 7-9% gross. Do not conflate the two.
Wynn Al Marjan Island opens 2027, the first legal casino in the Arab world. Al Marjan prices rose 16-17% YoY on speculative buying. Off-plan launches on Al Marjan trade at AED 2,400-3,200 per sqft, up sharply from 2022 levels. The appreciation thesis depends on Wynn delivering expected visitor volumes. Comparable casino openings in Singapore and Macau produced 40-80% surrounding real estate appreciation over 5 years.
RAK Properties (Mina Al Arab), Al Hamra Real Estate (Al Hamra Village), RAKEEN, and a wave of international developers on Al Marjan Island including branded residence operators. Developer track records are shorter than Dubai, project-level due diligence is essential.
Al Marjan Island apartments launch from AED 800K-2M+ for studios and one-beds. Branded residences run AED 2M-5M+. Mina Al Arab apartments from AED 600K-1.2M. Al Hamra extensions from AED 700K-2M. Villas on Al Marjan and Al Hamra start from AED 2M-5M+.
Al Marjan at current launch prices: 3-5% gross long-term, potentially higher STR post-Wynn. Mina Al Arab: 6-8% gross. Al Hamra established: 7-9% gross. Net yields are 1.5-3 points below gross depending on service charges and management.
Yes, in designated freehold zones including Al Marjan Island, Al Hamra Village, and Mina Al Arab. Register with RAK Land Department. Golden Visa threshold is AED 2 million, same as Dubai. Verify freehold designation on SPA.
RAK offers 35-45% lower psf than Dubai Marina for beach-resort product, with a specific Wynn catalyst Dubai lacks. Trade-offs: thinner secondary liquidity, smaller tenant base, longer commute to Dubai employment (45-60 minutes). RAK suits long-hold capital plays; Dubai suits liquidity and yield diversity.
Wynn delay or underperformance, Al Marjan oversupply (multiple branded residences launching simultaneously), thin secondary market for exit, low yield at current Al Marjan pricing, and developer track record gaps on newer Al Marjan builders.
Related reading: Best Off-Plan Areas in Dubai · Off-Plan Payment Plans in Dubai.
Related reading: UAE Golden Visa Property Requirements · Dubai Property Investment Guide.
Get a Gulf property shortlist
Tell us your budget and target market. Independent research first; enquiries are matched with licensed local partners. We reply within one business day.